Underwriting Conditions Explained: Why You Keep Getting Asked for More Documents
Getting approved for a mortgage feels great until the emails asking for more paperwork start rolling in. It can feel like the lender is looking for reasons to deny your loan. In reality, being asked for additional documentation is a completely normal part of crossing the finish line.
The Standard Document Request
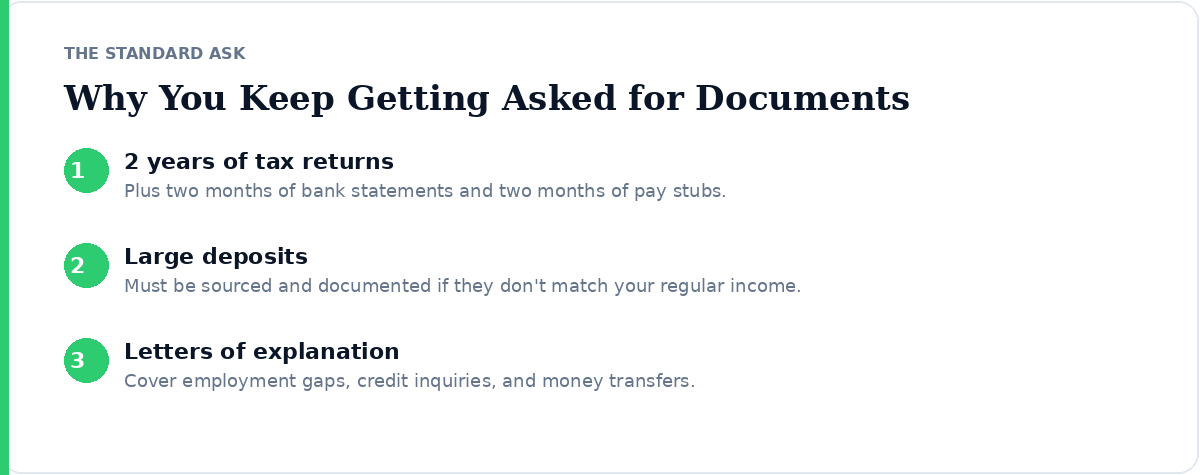
Every loan starts with a baseline of paperwork. Underwriters typically request the last two years of tax returns, two months of bank statements, and two months of pay stubs. Most buyers get a "conditional approval" initially. This means the loan is approved pending a list of conditions such as updated documents, explanations, or verification of deposits or income changes.
Explaining the Details
Underwriters are required to verify the exact source of your funds. Large deposits in the last two months that don't match regular income usually need to be sourced and documented. Recent large deposits, recent credit inquiries, and money transfers commonly trigger requests for explanation letters. If you use gifted money toward your home buying expenses, it typically requires a gift letter.
Letters of Explanation
Do not panic if you are asked to write a letter. A recent employment gap may require a simple letter of explanation clarifying the gap and why it happened. These letters are not a sign that something is wrong. They are just the underwriter's way of painting a complete, documented picture of your financial life for the final file.
Your Loan Officer is here to help you gather exactly what the underwriter needs. Our Mortgage Brokerage works hard to clear your conditions quickly so you can get your keys.
Expect to close one week early.
Frequently Asked Questions
Why does the underwriter keep asking for more documents after I'm already approved?
Initial approvals are "conditional," meaning the underwriter needs specific follow-up documents to finalize and verify the details of your file.
What is a mortgage underwriting "condition"?
A condition is a specific requirement from the underwriter, like an updated bank statement or a letter of explanation, that must be met before final approval.
Why do large deposits in my bank account need to be explained?
Underwriters must legally verify that large deposits are your own funds and not undisclosed new loans that would alter your debt-to-income ratio.
What is a letter of explanation and when do I need one?
It is a brief document written by you clarifying a specific financial event, such as an employment gap, a credit inquiry, or a large deposit.